How Does Extra Virgin Olive Oil Support a Balanced Diet?

Extra Virgin Olive Oil can support a balanced diet because it provides unsaturated fats and other naturally occurring compounds. People use Olive Oil in cooking, salad dressings, marinades, and many everyday meals. Its mild taste also works well with vegetables, grains, legumes, fish, and other foods.

Nutrition plays an important role in a Balanced Diet. The body needs different nutrients from different food groups. Healthy fats can provide energy and help the body absorb certain fat-soluble vitamins. Extra Virgin Olive Oil can provide these fats while adding flavour to meals.

A balanced eating pattern should include vegetables, fruits, whole grains, protein foods, and healthy sources of fat. Extra Virgin Olive Oil can fit into this pattern as one source of dietary fat. Portion size still matters because Olive Oil contains a high amount of calories per tablespoon.

What Is Extra Virgin Olive Oil?

Extra Virgin Olive Oil comes from olives and uses mechanical methods without extensive chemical processing. This type of Olive Oil retains many natural compounds found in fresh olives. Its flavour can range from mild and smooth to strong and peppery, depending on the olives and production process.

Extra Virgin Olive Oil is different from refined olive oil. The production process affects flavour, aroma, and the amount of naturally occurring compounds that remain in the oil. Extra Virgin Olive Oil also has specific quality standards that distinguish it from other grades of Olive Oil.

People can use Extra Virgin Olive Oil as part of everyday Nutrition. It can replace some sources of saturated fat in meals. For example, a person can use it in a salad dressing instead of a creamy dressing or use it with vegetables instead of large amounts of butter.

Extra Virgin Olive Oil and Healthy Fats

Dietary fat is an important part of human Nutrition. The body uses fat for energy and needs dietary fat to absorb vitamins A, D, E, and K. Fat also contributes to the structure of cell membranes and supports several normal body functions.

Extra Virgin Olive Oil contains mostly monounsaturated fat, especially oleic acid. Monounsaturated fats can be part of a heart-friendly eating pattern when they replace some saturated fats.

The type of fat in the overall diet matters. Replacing foods high in saturated fat with foods that provide unsaturated fats can improve the quality of the diet. Extra Virgin Olive Oil can help people make this type of food choice.

Extra Virgin Olive Oil and a Balanced Diet

A balanced diet includes different food groups and provides a wide range of nutrients. Extra Virgin Olive Oil can contribute healthy fats to meals, but it does not provide all the nutrients the body needs. Vegetables provide fibre, vitamins, minerals, and other plant compounds, while fruits provide carbohydrates, fibre, vitamins, minerals, and natural plant compounds.

Whole grains provide carbohydrates, fibre, vitamins, and minerals, while beans, lentils, eggs, fish, poultry, dairy foods, nuts, and seeds provide protein and other essential nutrients. For shoppers in Dubai, New Day Naturals can be a convenient option for finding quality olive oil and other natural food products that fit into a balanced eating pattern.

Extra Virgin Olive Oil can complement these foods when added to roasted vegetables, whole grains, beans, salads, or cooked meals. This approach allows Olive Oil to support a varied diet instead of becoming the main focus of daily nutrition.

How Olive Oil Can Improve Meal Quality

Olive Oil can make simple foods easier to enjoy. Some people may eat more vegetables when they prepare them with herbs, spices, lemon juice, and a small amount of Olive Oil.

For example, a vegetable salad can contain leafy greens, tomatoes, cucumbers, carrots, beans, and Extra Virgin Olive Oil. This meal can provide fibre, vitamins, minerals, protein, and healthy fats.

Olive Oil can also improve the taste of whole grains and legumes. A small amount can add flavour to brown rice, quinoa, lentils, chickpeas, or whole-grain bread. These combinations can help create meals with a wider range of nutrients.

Extra Virgin Olive Oil and Antioxidant Compounds

Extra Virgin Olive Oil contains naturally occurring antioxidant compounds called polyphenols. The amount and type of these compounds can vary based on factors such as olive variety, harvesting conditions, and production methods.

Polyphenols are plant compounds that researchers study for their potential role in health. Extra Virgin Olive Oil provides these compounds along with its main fat content.

A healthy diet should include many plant foods because different foods provide different types of plant compounds. Extra Virgin Olive Oil can contribute to this dietary variety, but it should not replace vegetables, fruits, whole grains, or other nutritious foods.

Extra Virgin Olive Oil and Heart Health

Heart health depends on many factors, including diet, physical activity, body weight, blood pressure, cholesterol levels, smoking status, and family history. No single food can determine a person’s overall heart health.

Extra Virgin Olive Oil can support a heart-friendly diet when it replaces foods high in saturated fat. Its high content of monounsaturated fat makes it a useful option for people who want to increase unsaturated fats in their diet.

Research on Mediterranean-style eating patterns has also linked regular use of Olive Oil with positive health outcomes. These eating patterns include vegetables, fruits, whole grains, legumes, nuts, fish, and moderate amounts of other foods.

The overall eating pattern matters more than one ingredient. Extra Virgin Olive Oil can be one part of that pattern.

Olive Oil and Vitamin Absorption

Some vitamins need dietary fat for proper absorption. Vitamins A, D, E, and K are fat-soluble vitamins. Eating these nutrients with a source of dietary fat can help the body absorb them.

For example, a salad containing leafy green vegetables provides vitamin K and other nutrients. Adding Extra Virgin Olive Oil to the salad provides dietary fat that can support the absorption of fat-soluble nutrients.

This does not mean that people need large amounts of oil with every meal. A moderate amount of healthy fat can fit into a Balanced Diet while helping create a nutritious and satisfying meal.

Using Extra Virgin Olive Oil With Vegetables

Vegetables are a key part of a Balanced Diet. They provide fibre, vitamins, minerals, and many plant compounds. Extra Virgin Olive Oil can work well with both raw and cooked vegetables.

People can use Olive Oil as a salad dressing with lemon juice, vinegar, herbs, and spices. They can also drizzle a small amount over cooked vegetables before serving.

Roasted vegetables can also work well with Extra Virgin Olive Oil. Vegetables such as carrots, peppers, zucchini, broccoli, cauliflower, and eggplant can be combined with herbs and spices to create a nutrient-rich meal.

This combination can improve flavour while adding healthy fat to the meal.

Extra Virgin Olive Oil and Mediterranean-Style Eating

The Mediterranean diet is a dietary pattern that commonly includes vegetables, fruits, legumes, whole grains, nuts, seeds, fish, and Olive Oil. Extra Virgin Olive Oil is a common source of added fat in this eating pattern.

This type of diet focuses on food variety and regular consumption of plant foods. It also includes moderate amounts of fish, poultry, dairy foods, and other protein sources.

The value of the Mediterranean diet comes from the complete eating pattern. Extra Virgin Olive Oil is one component of that pattern. People should also eat a wide range of nutrient-rich foods to meet their Nutrition needs.

How Much Extra Virgin Olive Oil Should You Use?

Extra Virgin Olive Oil provides a high amount of calories because dietary fat contains about nine calories per gram. For this reason, portion size matters even when the oil is a healthy source of fat.

The right amount depends on a person’s overall calorie needs, food choices, and health goals. A small amount can add flavour and healthy fat to a meal without adding excessive calories.

People can measure Olive Oil with a spoon instead of pouring it directly from the bottle. This simple habit can help control portions while allowing people to enjoy the flavour and nutritional benefits of the oil.

Choosing Quality Extra Virgin Olive Oil

Quality can affect the flavour and characteristics of Extra Virgin Olive Oil. Consumers should check the product label and storage information when buying Olive Oil.

Extra Virgin Olive Oil should be stored away from heat, light, and air. A cool and dark cupboard can help protect the oil from quality loss. The bottle should remain tightly closed when it is not being used.

Dark bottles or containers can provide additional protection from light. Consumers should also follow the storage instructions provided on the product.

Extra Virgin Olive Oil in Everyday Meals

People can use Extra Virgin Olive Oil in many simple meals. They can add it to salads, vegetables, grains, beans, soups, and homemade dressings.

For breakfast, a person can use a small amount of Olive Oil with eggs and vegetables. For lunch, Olive Oil can work as part of a salad dressing with leafy greens, beans, tomatoes, and whole grains.

For dinner, people can use Extra Virgin Olive Oil with roasted vegetables, fish, legumes, or whole grains. These combinations can create meals that provide healthy fats along with protein, fibre, vitamins, and minerals.

The goal is to use Olive Oil as part of a varied eating pattern.

Extra Virgin Olive Oil and Calorie Balance

Healthy food choices still require attention to total calorie intake. Extra Virgin Olive Oil contains healthy fats, but it remains a calorie-dense food.

Adding large amounts of oil to meals can increase calorie intake quickly. People who want to maintain or reduce body weight should consider the amount of Olive Oil they use along with the calories from other foods.

A Balanced Diet should provide enough energy and nutrients for the person’s needs. Portion control can help people include Extra Virgin Olive Oil without consuming more calories than they need.

Common Mistakes When Using Olive Oil

One common mistake involves treating Olive Oil as a complete source of Nutrition. Olive Oil provides healthy fats and other compounds, but it does not provide enough protein, fibre, or many essential vitamins and minerals to replace a varied diet.

Another mistake involves using very large amounts because the oil is considered healthy. Healthy fats still contain calories, so portion size remains important.

Some people also store Extra Virgin Olive Oil near a stove or another heat source. Excessive heat can reduce oil quality over time. Proper storage can help maintain its flavour and quality.

How Extra Virgin Olive Oil Fits Into Healthy Eating

Extra Virgin Olive Oil can support healthy eating when people use it as part of a varied diet. It provides mostly monounsaturated fat and contains naturally occurring plant compounds.

A Balanced Diet should include vegetables, fruits, whole grains, legumes, protein foods, and healthy sources of fat. Olive Oil can provide one source of that healthy fat.

People can use Extra Virgin Olive Oil in salads, cooked vegetables, grains, beans, and homemade dressings. They should also pay attention to portion sizes because the oil contains many calories.

Conclusion

Extra Virgin Olive Oil can support a Balanced Diet by providing unsaturated fat and naturally occurring plant compounds. It can help replace some sources of saturated fat and can add flavour to nutritious meals.

Nutrition depends on the complete diet rather than one food. Vegetables, fruits, whole grains, legumes, protein foods, nuts, seeds, and healthy fats all have a role in a balanced eating pattern.

Using Olive Oil in moderate amounts can make healthy meals more enjoyable while adding an important source of dietary fat. When combined with a wide range of nutrient-rich foods, Extra Virgin Olive Oil can be a practical part of everyday healthy eating.
How Is Gratuity Calculated After 5 Years in Saudi Arabia?

Gratuity is an important employment benefit for workers in Saudi Arabia. Employees who complete a required period of service may receive an end-of-service benefit when their employment ends. The calculation depends on the employee’s final wage, total service period, and the reason for leaving the job. Understanding how gratuity is calculated helps employees estimate the amount they may receive after completing five years of service.

In Saudi Arabia, the end-of-service benefit is generally calculated under the Saudi Labor Law. The calculation uses different portions of the employee’s wage based on the length of service. The employee receives half a month’s wage for each of the first five years of service and one full month’s wage for each year after the first five years, subject to the applicable rules and exceptions.

What Is Gratuity in Saudi Arabia?

Gratuity in Saudi Arabia refers to the end-of-service benefit that an employer may owe an employee when the employment relationship ends. The benefit rewards employees for their period of service with the employer. Saudi employment rules set the general method for calculating this benefit.

The calculation usually considers the employee’s last wage and completed years of service. An employee who completes five years can receive a gratuity based on half a month’s wage for each of those five years. This means five completed years generally equal 2.5 months of the employee’s wage under the standard calculation.

The final amount can change based on the employee’s employment contract, applicable labor rules, reason for termination, and other legal factors. Employees should therefore check their employment records before calculating the final amount.

How Is Gratuity Calculated After 5 Years in Saudi Arabia?

Saudi Arabia uses a service-based formula for the end-of-service benefit. For the first five years of service, the employee generally receives half of the monthly wage for each completed year.

The basic formula for five completed years is:

Gratuity = Half Monthly Wage × 5 Years

This calculation gives a total of 2.5 months of the employee’s wage.

For example, suppose an employee earns SAR 6,000 as the wage used for the gratuity calculation. The calculation would be:

Half of SAR 6,000 = SAR 3,000

SAR 3,000 × 5 years = SAR 15,000

In this example, the employee would receive SAR 15,000 under the standard five-year calculation.

The actual amount can depend on which wage components count under the applicable rules. Employees should therefore confirm the wage basis before relying on an estimate.

Gratuity Calculation Example for a SAR 5,000 Salary

An employee with a monthly wage of SAR 5,000 can calculate the benefit after five completed years by using half of the monthly wage.

Half of SAR 5,000 equals SAR 2,500.

The employee then multiplies SAR 2,500 by five completed years.

The total gratuity would be SAR 12,500 under the standard calculation.

This example shows why the final wage plays an important role. A higher wage generally produces a higher end-of-service benefit when the same service period applies.

Gratuity Calculation Example for a SAR 8,000 Salary

Consider an employee who earns SAR 8,000 per month and completes five years of service. Half of the monthly wage is SAR 4,000.

The calculation becomes:

SAR 4,000 × 5 = SAR 20,000

The estimated gratuity would therefore be SAR 20,000 under the standard formula for five completed years.

Employees can use the same method with their own wage. They should first identify the wage that applies to the gratuity calculation and then multiply half of that amount by the number of completed years within the first five-year period.

What Happens After the First 5 Years?

The gratuity calculation changes after the employee completes the first five years of service. Saudi Arabia generally provides half a month’s wage for each year during the first five years. After that period, the calculation generally changes to one full month’s wage for each additional year.

For example, an employee who completes seven years of service would calculate the first five years using half a month’s wage for each year. The remaining two years would generally use one full month’s wage for each year.

Suppose the applicable monthly wage is SAR 6,000. The first five years would produce SAR 15,000. The next two years would produce SAR 12,000.

The total would therefore be SAR 27,000 under this standard example.

The calculation can differ in certain situations, so employees should check the applicable employment rules and contract terms.

Does the Reason for Leaving Affect Gratuity?

Yes. The reason for ending employment can affect the amount of the end-of-service benefit in certain cases. Saudi employment rules contain provisions for different types of employment termination and resignation.

An employee who leaves voluntarily may have different entitlement rules from an employee whose employment ends through employer termination. The employee’s total service period can also affect the entitlement in cases of resignation.

For this reason, employees should not calculate gratuity based only on salary and years of service. They should also consider how the employment relationship ended.

The employment contract can provide additional information about termination and benefits, but contractual terms must comply with applicable Saudi labor requirements.

What If an Employee Resigns After 5 Years?

Resignation can have a specific effect on end-of-service benefits. The employee’s service period matters when determining the applicable entitlement.

An employee who has completed five years of continuous service may have different entitlement treatment from an employee who resigns after a shorter period. The exact calculation depends on the applicable Saudi employment rules and the circumstances of the resignation.

Employees should review their resignation date, contract, total service period, and wage records before estimating the final amount. They should also check the current Saudi Labor Law provisions that apply to their employment.

Does Continuous Service Matter?

Continuous service plays an important role in gratuity calculations. The employer normally uses the employee’s recognized period of service to calculate the end-of-service benefit.

An employee should keep accurate records of the employment start date and end date. Even a difference of several months can affect the calculation because the total service period changes.

For example, an employee who completes exactly five years has a different service period from an employee who completes five years and six months. The calculation may account for parts of a year according to the applicable rules.

Employees should therefore use their actual employment dates rather than estimating the service period by calendar years alone.

Which Salary Is Used for Gratuity Calculation?

The wage used for the gratuity calculation is an important part of the process. Employees may receive different types of payments, including basic salary, housing allowance, transport allowance, commissions, and other benefits.

The applicable Saudi employment rules determine which wage components should be included in the calculation. Employees should therefore avoid assuming that basic salary alone will always determine their final gratuity amount. Using an End of Service Calculator can help employees estimate their potential entitlement based on the relevant salary components and length of service.

Before calculating the expected benefit, employees should review their employment contract and salary structure. They should identify which wage amount applies under the relevant legal provisions and ensure that the calculation reflects their actual employment details.

This approach can help reduce differences between an employee’s personal estimate and the final gratuity amount calculated by the employer.

Is Gratuity Paid Automatically When Employment Ends?

The employer generally becomes responsible for settling the employee’s final employment dues when the employment relationship ends, subject to the applicable legal requirements and circumstances.

Final employment dues can include salary, unused leave payments where applicable, and end-of-service benefits. The exact settlement depends on the employee’s employment situation and applicable Saudi rules.

Employees should review the final settlement carefully. They should compare the amount with their employment records, salary information, service dates, and contractual terms.

If an employee believes that the employer has not paid the correct amount, the employee can use the relevant Saudi labor dispute and employment services available through the Ministry of Human Resources and Social Development.

Simple Formula for Five Years of Service

The standard calculation for five completed years can be expressed in a simple way.

An employee first identifies the applicable monthly wage. The employee then divides that wage by two. The result is multiplied by five.

For example, if the applicable wage is SAR 7,000:

SAR 7,000 ÷ 2 = SAR 3,500

SAR 3,500 × 5 = SAR 17,500

The estimated gratuity is SAR 17,500 under the standard five-year calculation.

This formula provides a simple starting point for employees who want to estimate their end-of-service benefit.

Factors That Can Change the Final Amount

Several factors can affect the final gratuity amount in Saudi Arabia. The employee’s total service period is one of the main factors. The wage used for the calculation is another important factor.

The reason for employment termination can also affect entitlement. Resignation rules can differ from termination rules. Contract terms and specific employment circumstances can also influence the final settlement where permitted by law.

Employees should also consider whether their service includes periods that require special treatment under the applicable rules. Accurate employment dates and salary records can help produce a more reliable estimate.

Final Thoughts on Gratuity in Saudi Arabia

Gratuity is an important part of the final employment settlement in Saudi Arabia. After five completed years, the standard calculation generally provides half a month’s wage for each year of service during the first five years. This results in an amount equal to 2.5 months of the applicable wage.

For example, an employee with an applicable monthly wage of SAR 6,000 would receive an estimated SAR 15,000 under the standard five-year formula.

The final amount can depend on the employee’s wage, service period, reason for leaving, contract, and applicable Saudi employment rules. Employees should use their official employment records and current legal requirements for an accurate calculation.

How to Monitor Your Debt Balance From Month to Month

Managing debt becomes easier when you know how much you owe, how much you have paid, and how your balance changes each month. A clear record helps you track progress and keep your payments on schedule. You can use a simple spreadsheet, a banking app, or a debt payoff planner to record your payments and check your Debt Balance.

Regular tracking also helps you identify changes in interest, fees, and payment amounts. A monthly review gives you a clear view of your debt and shows how each payment affects the remaining balance. This process can help you create a practical repayment plan and avoid missed payments.

What Is a Debt Balance?

A Debt Balance is the amount of money you still owe on a loan, credit card, or other debt account. The balance can change after each payment, interest charge, fee, or new purchase. Your lender usually shows the current balance on your monthly statement or online account.

For example, assume you have a credit card balance of $5,000. You make a $400 payment during the month. If the lender adds $75 in interest, your new balance may be $4,675 before any other charges. This example shows why you should check the balance after each billing cycle instead of tracking payments alone.

Your balance can include several parts. These parts may include the principal amount, interest, late fees, annual fees, and other charges. Understanding these amounts helps you see where your money goes each month.

Why Should You Monitor Debt Balance Each Month?

You should Monitor Debt Balance each month because debt can change even when you make regular payments. Interest can increase the amount you owe, while extra payments can reduce the principal faster. Monthly monitoring shows the actual result of your repayment activity.

Regular checks also help you find errors. A statement may include an unexpected fee or charge. You can contact the lender if a transaction does not match your records. Early action can prevent a small issue from becoming a larger problem.

Monthly monitoring also gives you a clear repayment target. You can compare your current balance with the balance from the previous month. This comparison shows whether your debt is decreasing at the rate you expect.

Gather Your Debt Information

Start by collecting the information for every debt account. You should record the account name, current balance, interest rate, minimum payment, payment due date, and statement date. You should also record any fees that can affect the balance.

You can find most of this information on your monthly statement or lender account. Keep the information in one place so you can review all debts together. A spreadsheet can work well for this purpose because you can update the numbers every month.

If you have several debts, create a separate record for each account. Include credit cards, personal loans, student loans, auto loans, and other outstanding balances. A complete record gives you a better view of your total debt.

Record Your Starting Debt Balance

Choose a specific date as your starting point. Record the balance for every debt on that date. This amount becomes your starting Debt Balance for monthly comparisons.

For example, you may start January with $12,000 in total debt. You can record the amount for each account separately. If your credit card balance is $4,000 and your personal loan balance is $8,000, your total starting debt is $12,000.

Keep the starting numbers unchanged in your records. Add new monthly balances below them. This method creates a simple history that shows how your debt changes over time.

Track Every Monthly Payment

Record every payment that you make during the month. Include the payment date and payment amount. You should also record whether the payment was a minimum payment or an extra payment.

Suppose your loan balance starts at $8,000. You pay $500 during the month. The lender applies part of the payment to interest and part to the principal. The exact principal reduction depends on the loan terms. Your next statement will show the updated balance.

Tracking payments helps you understand your progress. It also helps you confirm that the lender received your payments correctly.

Check Interest and Fees

Interest can slow down debt repayment. Fees can also increase your Debt Balance. For this reason, you should review these charges during every monthly check.

Look at the interest amount on your statement. Compare it with the previous month when possible. If the interest rate changes, note the new rate in your records.

You should also check for late fees, annual fees, cash advance fees, or other charges. These costs can affect your repayment timeline. A payment may seem large, but your balance may decrease slowly if the account adds significant interest each month.

Calculate Your Total Debt Balance

Add the balances from all your debt accounts at the end of each month. This number gives you your total Debt Balance.

For example, assume you have three accounts. Your credit card balance is $2,500, your personal loan balance is $6,000, and your auto loan balance is $9,500. Your total debt is $18,000.

The next month, the balances may fall to $2,300, $5,700, and $9,300. Your new total debt is $17,300. Your total balance has dropped by $700. This calculation gives you a simple way to measure monthly progress.

Use a Debt Payoff Planner

A Debt payoff planner can help you organise your repayment schedule. The planner can show your current balance, monthly payment, interest rate, and expected payoff date.

You can update the planner after every monthly statement. Enter the new balance and payment information. The planner can then help you compare your actual progress with your planned progress.

A Debt payoff planner can also help you compare different payment strategies. For example, you may want to pay the debt with the highest interest rate first. Another approach may focus on paying the smallest balance first. The best method depends on your financial situation, interest rates, payment requirements, and personal goals.

Compare Your Current Balance With Last Month

A monthly comparison gives you a clear picture of progress. Subtract your current balance from the previous balance to see how much the debt changed.

For example, if your balance was $10,000 last month and $9,400 this month, your balance decreased by $600. If the balance increased, review your statement to find the reason.

A balance can increase because of interest, new purchases, fees, or missed payments. The comparison helps you identify the cause and adjust your payment plan if needed.

Set a Monthly Debt Review Date

Choose one day each month to Monitor Debt Balance. You can use the same date as your statement date or choose another convenient day. A fixed schedule makes debt tracking easier.

During the monthly review, check each account and update your records. Record the new balance, payments, interest, fees, and any other changes. Then calculate your total debt.

A short monthly review can prevent your debt records from becoming outdated. It also gives you a regular opportunity to review your repayment plan.

Monitor Your Debt-to-Income Ratio

Your debt-to-income ratio compares your monthly debt payments with your gross monthly income. This ratio can help you understand how much of your income goes toward debt payments.

For example, if your gross monthly income is $5,000 and your required monthly debt payments total $1,000, your debt-to-income ratio is 20%.

The ratio can change as your income or debt payments change. Tracking it alongside your Debt Balance gives you a broader view of your financial position. A lower balance can reduce your required payments over time, depending on the type of debt and loan terms.

Avoid Adding New Debt While Paying Existing Debt

New debt can slow your repayment progress. If you continue adding new balances while making payments, your total Debt Balance may decrease slowly or increase.

Review your spending before using a credit card for new purchases. If you need to use credit, record the new charge in your monthly debt records. This keeps your tracking accurate.

A clear spending plan can also help you control new debt. Set limits for discretionary spending and keep enough money available for required debt payments.

Review Your Debt Payoff Progress Every Three Months

Monthly tracking shows short-term changes, but a three-month review can show a larger trend. Compare your total Debt Balance from three months ago with your current balance.

Look at the amount you paid, the interest charged, and the amount by which your principal decreased. This review can show whether your current repayment plan is working as expected.

If your balance has not decreased as planned, review your payment amount and interest costs. You may need to increase your payment, reduce new borrowing, or change the order in which you repay your debts.

Keep Your Debt Records Accurate

Accurate records make debt tracking more useful. Update your records after each payment and monthly statement. Check the numbers against your lender’s records.

Keep copies of statements and payment confirmations when possible. These records can help you resolve account issues and confirm your payment history.

You should also protect your financial information. Use secure passwords for financial accounts and avoid storing sensitive account details in unsecured locations.

Create a Long-Term Debt Monitoring Routine

A long-term routine can make debt management easier. Start each month by checking your account balances and upcoming payments. Record all new charges and payments during the month. At the end of the billing cycle, update your Debt Balance and compare it with the previous month.

Use a Debt payoff planner to connect your monthly records with your larger repayment goal. Review your progress every few months and adjust your plan when your income, expenses, interest rates, or debt balances change.

The main goal is to keep a clear record of what you owe and how quickly the balance changes. When you Monitor Debt Balance consistently, you can make informed decisions about payments and spending. Regular tracking also gives you a clear record of your progress from one month to the next.

Preventing Sample Confusion in High-Density Assays

High-density assays allow researchers to process many samples in a small laboratory space. This approach can increase testing capacity and reduce reagent use. However, a high number of samples also increases the risk of sample confusion. A single labeling error, pipetting mistake, or plate position error can affect assay results. Clear sample identification is therefore important for reliable laboratory work. Researchers can reduce confusion by using consistent labels, organized plate maps, controlled workflows, and careful sample handling. The 96-well plate format is common for high-density assays because it provides a practical layout for processing many samples at the same time.

Understanding Sample Confusion in High-Density Assays

Sample confusion occurs when a sample receives the wrong identity or when researchers cannot confirm its correct position in an assay. High-density assays can increase this risk because many samples occupy a limited physical area. Using a 96 Well Plate Template: https://96wellplatetemplate.com/ can help researchers establish a consistent plate layout and clearly assign each sample to its designated well before the experiment begins. In a 96-well plate, each well has a specific position, such as A1, A2, B1, or B2.

Researchers must connect each position with the correct sample throughout the assay process. Confusion can occur during sample preparation, plate loading, reagent addition, incubation, transfer, or result analysis. Even a small mistake can connect the wrong result with the wrong sample. A clear identification system helps researchers maintain sample identity from the beginning of the assay to the final data review.

Why the 96-Well Plate Format Requires Careful Organization

The 96-well plate format contains eight rows and twelve columns. This structure gives researchers 96 individual wells for sample processing. The compact layout supports efficient laboratory workflows, but it also creates many opportunities for position errors. Adjacent wells can contain different samples, controls, standards, or blanks. A researcher can easily move one position to the left or right during manual pipetting. A poorly organized plate map can also cause confusion during data entry. Researchers should therefore establish a fixed plate layout before starting the assay. The same layout should remain consistent throughout sample preparation, testing, and data analysis.

Using Clear Plate Maps

A plate map provides a record of what each well contains. The map should identify sample numbers, controls, standards, and other assay components. Researchers should prepare the map before loading the plate. The sample identification on the map should match the identification used on sample tubes and laboratory records. For example, sample S001 should have the same identifier in the sample record and the corresponding plate position. Researchers should avoid relying on memory when working with high-density assays. A written or electronic plate map provides a reference that researchers can check during every stage of the assay.

Creating a Consistent Sample Numbering System

A consistent numbering system reduces confusion between samples. Each sample should have a unique identifier. Researchers should avoid using similar identifiers that can be difficult to distinguish. A system such as S001, S002, and S003 provides a clear sequence. The identifier should remain unchanged throughout the assay. Researchers should also avoid renaming samples during data analysis because name changes can break the connection between physical samples and recorded results. A stable identification system makes it easier to trace each result back to the correct sample.

Separating Samples, Controls, and Standards

High-density assays often contain different types of wells. Sample wells contain test material, while control and standard wells support assay validation and result interpretation. Researchers should separate these categories clearly in the plate layout. A fixed arrangement can make the plate easier to read and reduce the risk of accidental sample placement. For example, researchers may reserve specific areas for controls and standards and use the remaining wells for samples. The exact layout should match the requirements of the assay. The key goal is to use a predictable structure that reduces decisions during plate loading.

Keeping Controls in Fixed Positions

Controls should have consistent positions whenever possible. A fixed control location allows researchers to identify control wells quickly. It also helps during data analysis because the same positions can be recognized across multiple plates. Researchers should record control positions in the plate map and verify them before starting the assay. If an assay requires positive controls, negative controls, or blank wells, each type should have a clear identifier. Consistent control placement can also make it easier to identify plate-level problems during result review.

Labeling Samples Before Plate Loading

Sample labeling should take place before samples enter the plate workflow. Each tube should have a readable and unique identifier. The label should remain attached during the full handling process. Researchers should compare the tube identifier with the sample record before transferring material to the plate. This verification step helps prevent an incorrect sample from entering the wrong well. Researchers should avoid labels that depend only on color because colors can be difficult to distinguish under different lighting conditions. A unique written or coded identifier provides stronger sample tracking.

Checking Sample Identity at Each Transfer

Sample identity can become unclear when material moves between tubes, racks, and plates. Researchers should verify the sample identifier before each important transfer. The verification should confirm both the sample identity and the intended plate position. A second check can be useful when a large number of samples are processed. This process reduces the chance of carrying an earlier labeling error into the next stage. Researchers should record any unexpected sample position or handling issue immediately instead of trying to reconstruct the event later.

Reducing Pipetting Errors in High-Density Assays

Pipetting errors can cause sample confusion even when the original sample labels are correct. A researcher may accidentally dispense a sample into an adjacent well or skip a well during manual loading. High-density assays require controlled movement across the plate. Researchers should follow the same direction and sequence for every plate. For example, a researcher can work across each row in a fixed order or move down each column using a defined sequence. The selected method should remain consistent for the entire assay. Clear working patterns reduce unnecessary movement and make errors easier to detect.

Using a Defined Loading Sequence

A defined loading sequence tells the researcher exactly which sample should enter each well. The sequence should match the plate map. Researchers should avoid changing the sequence during the assay unless the change is recorded. If the workflow requires a change, the plate map should be updated immediately. A defined sequence is especially useful when researchers process several 96-well plates at the same time. Each plate should have its own clear identity and loading record. This approach prevents samples from different plates from being confused.

Managing Multiple 96-Well Plates

Processing multiple plates increases the number of sample positions that researchers must track. Each plate should have a unique plate identifier. The identifier should appear on the physical plate and in the electronic record. Researchers should also record which samples belong to each plate. A system such as Plate 01, Plate 02, and Plate 03 provides a simple structure for tracking. Researchers should avoid placing unmarked plates next to each other because this can create confusion during handling and data analysis. Clear plate identification becomes increasingly important as assay volume increases.

Recording Plate Position and Sample Identity

Sample identity should connect directly to the plate identifier and well position. A complete record can show the plate number, well position, and sample identifier. This structure gives each sample a clear location within the assay. For example, a record can associate Sample S014 with Plate 02 and position C06. Researchers can then identify the physical well and the related result without relying on memory. This record also helps during result review when researchers need to investigate an unexpected finding.

Using Electronic Tracking for Assay Records

Electronic tracking can reduce manual transcription errors in high-density assays. Researchers can store plate maps, sample identifiers, and result records in a controlled system. Electronic records can also make it easier to search for a sample or confirm its plate position. However, electronic systems still depend on accurate information. A wrong sample identifier entered into a system can create a reliable record of incorrect information. Researchers should therefore verify electronic records against the physical plate and original sample records before final analysis.

Reviewing Data Before Final Results

Data review provides an important opportunity to identify sample confusion. Researchers should compare the final result file with the original plate map. The review should confirm sample identifiers, plate numbers, well positions, controls, and standards. Unexpected patterns can also indicate a possible handling or position error. For example, an unusual result in one well may require a review of the corresponding sample record. Researchers should investigate discrepancies before reporting final results. Early review can prevent an identification error from affecting later decisions.

Training Staff for High-Density Assays

Staff training can reduce errors during high-density assays. Researchers should understand the plate layout, sample identification system, pipetting sequence, and recording process before starting the assay. Training should also explain what to do when an error occurs. Staff should record errors immediately instead of attempting to correct records without documentation. Regular practice with the 96-well plate format can help researchers become familiar with row and column positions. A consistent workflow makes sample handling easier to repeat and review.

Maintaining a Standard Assay Workflow

A standard workflow gives researchers a consistent process for every assay. The workflow should define sample labeling, plate identification, plate mapping, sample loading, verification, result recording, and data review. Researchers should use the same process for similar assays whenever possible. A standard workflow reduces unnecessary changes and limits opportunities for confusion. It also helps different researchers follow the same process when several people work on the same project. Clear procedures make assay records easier to understand and review.

Final Checks Before Running High-Density Assays

A final check can identify problems before the assay begins. Researchers should confirm that every sample has a unique identifier and that the plate map matches the planned layout. They should verify the plate identifier, well positions, controls, standards, and sample sequence. Researchers should also check that physical labels match electronic records. This final review takes little time compared with the time required to investigate incorrect assay results. A clear pre-assay check can therefore reduce the risk of sample confusion.

Conclusion

Preventing sample confusion in high-density assays requires clear identification and consistent handling. The 96-well plate format can support efficient sample processing when researchers use an organized plate map and a fixed workflow. Unique sample identifiers, clear plate labels, defined loading sequences, fixed control positions, and accurate records help maintain sample identity. Electronic tracking can further support record management when researchers verify the information carefully. Regular data checks and staff training also reduce the risk of errors. By using the same identification and verification process for each assay, researchers can improve sample tracking and maintain reliable assay records.

How Changes in Income Can Affect Your Debt Plan

Income changes can affect how you manage debt. A higher income can give you more money for debt payments. A lower income can reduce the amount you can pay each month. Your debt plan should match your current income, expenses, and debt balance. A clear plan can help you control payments and track progress. You can use a Debt Payoff Tracker to record payments, check balances, and measure your progress. You should also review your Monthly Debt payments when your income changes. This review can help you avoid missed payments and keep your debt goals realistic.

How Income Affects Your Debt Plan

Your income determines how much money you have after basic expenses. This remaining money can support your debt payments. A stable income makes it easier to set a fixed payment amount. A higher income can allow you to increase payments and reduce debt faster. A lower income may require you to reduce extra payments until your financial situation improves.

Your Debt Plan should reflect your actual monthly income. You should not create a payment target that you cannot maintain. A plan should cover required debt payments first. It should also leave enough money for essential expenses. After these costs, you can decide how much extra money should go toward debt.

What Happens When Your Income Increases

An income increase can improve your ability to manage debt. A raise, bonus, new job, or extra source of income can increase the money available after regular expenses. You can use part of this extra money to increase your debt payments.

You should avoid increasing spending at the same rate as your income. For example, if your monthly income increases by $500, you do not need to spend the full $500 on new expenses. You can use part of the increase for debt payments. This approach can help you reduce balances faster without changing your basic lifestyle.

A higher income can also help you build an emergency fund while paying debt. An emergency fund can reduce the need to use credit cards or loans for unexpected costs. You can divide extra income between debt payments and savings based on your financial needs.

Use Extra Income to Reduce Debt

Extra income can support faster debt payoff. You can choose a fixed amount from every income increase and add it to your debt payment. For example, you may decide to use 50% of every raise for debt payments and keep the rest for savings or regular expenses.

This method creates a simple rule for your money. You do not need to make a new decision every month. You can update your Debt Payoff Tracker after each payment and record the new balance. The tracker can show how additional payments affect your payoff date.

What Happens When Your Income Decreases

A lower income can make debt payments harder to manage. Job loss, reduced working hours, business income changes, or other financial problems can reduce the money available for debt. You should review your budget as soon as your income drops.

Start by calculating your new monthly income. Then list essential expenses and required debt payments. Compare these costs with your available income. This process can show whether your current Debt Plan still works.

You may need to reduce optional spending before changing your debt payment strategy. You should focus on housing, food, utilities, transportation, insurance, and required debt payments. You should avoid taking new debt to cover regular expenses if possible.

Adjust Your Monthly Debt Payments

Your Monthly Debt payments should match your current ability to pay. You should continue making required payments on time whenever possible. If you cannot meet a required payment, contact the lender before the payment becomes overdue.

You may also need to pause extra debt payments for a short period. This does not mean you have failed. Your financial situation can change, and your plan should change with it. The main goal is to avoid missed payments and prevent your debt balance from growing because of new borrowing.

Why You Should Track Monthly Debt

Tracking Monthly Debt gives you a clear view of your financial obligations. Your monthly debt may include credit card payments, personal loans, student loans, auto loans, and other required payments. You should record each debt separately so you can see the amount due and the current balance.

Income changes can make these numbers more important. A higher income may allow larger payments. A lower income may require temporary changes. Regular tracking helps you see whether your payment plan still fits your budget.

A simple record can include the debt name, current balance, interest rate, minimum payment, extra payment, and remaining balance. You can update these numbers after each payment. This information can help you make better payment decisions.

How a Debt Payoff Tracker Can Help

A Debt Payoff Tracker can make debt management easier. It gives you one place to record balances and payments. You can use it to monitor your progress over time.

The tracker can also help you compare different payment amounts. For example, you can compare a $300 monthly payment with a $500 monthly payment. The difference can show how extra payments may reduce the payoff period.

You should update the tracker whenever your income changes. A new salary can change your payment target. A lower income can require a temporary adjustment. Keeping the tracker current helps you avoid using outdated numbers in your Debt Plan.

Update Your Tracker After Income Changes

You should update your Debt Payoff Tracker after a major income change. Record your new income and review your current expenses. Then check each debt balance and payment requirement.

If your income increases, enter the amount you can add to debt payments. If your income decreases, update the payment amount that you can safely maintain. The tracker should reflect your real financial situation instead of an old budget.

How to Prioritize Debt After an Income Increase

A higher income gives you more options. You can increase payments on one debt while maintaining minimum payments on others. Two common methods include the debt avalanche method and the debt snowball method.

The debt avalanche method focuses on debts with higher interest rates. Paying these debts first can reduce the amount of interest you pay over time. The debt snowball method focuses on smaller balances first. Paying a small balance can create a sense of progress and may help you stay motivated.

Your Debt Plan should use a method that you can follow consistently. The best method depends on your debt balances, interest rates, income, and personal preferences.

How to Prioritize Debt After an Income Decrease

A lower income requires a different approach. Your first goal should be to protect essential expenses and maintain required debt payments. You should review subscriptions, entertainment costs, dining expenses, and other optional spending.

You should also review your debt accounts. If you expect a temporary income reduction, you can create a short-term plan. If the income reduction may continue for several months, you may need a longer-term budget.

You should contact creditors if you cannot make required payments. Some lenders may offer payment options or hardship programs. You should understand the terms before accepting any new arrangement.

Create Different Debt Plans for Different Income Levels

Your financial plan does not need to use one payment amount for every situation. You can create different versions based on your income.

For example, you can create a standard plan for your normal income. You can create an aggressive plan for months with higher income. You can also create a reduced plan for months with lower income.

This approach can make income changes easier to manage. You already know how much you can pay under each situation. You can update your Debt Payoff Tracker and select the plan that matches your current income.

Build an Emergency Fund While Paying Debt

Income changes can create financial pressure. An emergency fund can help you handle unexpected costs without adding new debt. You should consider saving some money even while you work on debt payoff.

The right savings amount depends on your income, expenses, debt costs, and financial stability. You can start with a small amount and increase your savings as your income improves.

A higher income can support both goals. You can make extra debt payments while adding money to savings. A lower income may require you to focus more on essential expenses and basic savings until your income improves.

Review Your Debt Plan Regularly

Your Debt Plan should change when your financial situation changes. You should review your income, expenses, Monthly Debt payments, interest rates, and balances on a regular basis.

A monthly review can help you find problems early. You may notice that your expenses have increased or that your income has changed. You can then adjust your payment target before the problem affects your budget.

Your Debt Payoff Tracker can support this review. Update your balances and payments each month. Compare your current progress with your original plan. If your progress is slower or faster than expected, adjust your future payments.

Avoid Lifestyle Inflation After a Raise

A common problem after an income increase is lifestyle inflation. Lifestyle inflation happens when spending increases because income increases. New spending can reduce the amount available for debt payments and savings.

You do not need to avoid every new expense after a raise. You should set a clear limit for lifestyle increases. You can use the remaining income for debt reduction and savings.

For example, a $400 monthly raise could support an additional debt payment while allowing a smaller amount for personal spending. This approach lets you enjoy part of the income increase while still making progress on your debt.

Use Income Changes as a Reason to Review Your Goals

An income change gives you a reason to review your financial goals. You may want to become debt-free faster after receiving a raise. You may need to extend your payoff timeline after a temporary income reduction.

Your goals should remain realistic. A Debt Plan should help you manage debt without creating financial pressure that you cannot maintain. You should focus on consistent progress rather than setting payment targets that do not match your income.

Your Debt Payoff Tracker can help you measure this progress. Each payment reduces a balance. Each updated balance gives you a clear view of your current position.

Final Thoughts on Income and Debt Management

Changes in income can affect every part of your debt strategy. Higher income can create more money for debt payments and savings. Lower income can require spending cuts and temporary payment adjustments. The key is to keep your Debt Plan connected to your current financial situation.

You should review your Monthly Debt payments after every major income change. You should update your Debt Payoff Tracker regularly. You should keep required payments as a priority and avoid taking new debt when possible. A clear plan can help you respond to income changes without losing control of your debt goals.

A debt plan does not need to stay the same forever. Your income, expenses, balances, and financial goals can change. Regular reviews can help you adjust your payments and continue making steady progress.

Why Property Location Matters More Than Ever in Dublin

Finding the right property takes more than checking the size, price, or design. Property Location now plays a bigger role than ever before. Buyers and investors look at daily travel, nearby services, future growth, and long-term value before making a decision. A good location can improve quality of life and increase the value of a Property over time.

Dublin continues to attract people from different parts of Ireland and other countries. The city offers strong job opportunities, good schools, modern healthcare, and public transport. These factors increase demand for Property across many parts of Dublin. As demand grows, buyers pay closer attention to where a Property is located instead of focusing only on its features.

People now think about work, education, shopping, parks, and transport before buying a home. They also want a place that supports their daily routine. A good Property Location helps people save time, reduce travel costs, and enjoy a better lifestyle. This is why location remains one of the most important parts of every property decision.

Property Location Has a Direct Effect on Property Value

Property Location has always influenced property prices, but its impact has become even stronger in recent years. Homes in well-connected areas often keep their value better than homes in less popular locations. Buyers understand that a good location can offer both comfort and financial security.

Many areas in Dublin have seen steady price growth because they offer strong transport links, business centres, schools, and local services. A Property close to these facilities often attracts more buyers. Higher demand usually supports higher property values.

People also consider future development before buying. New roads, transport projects, business parks, and community facilities can increase demand for Property in nearby areas. Buyers who choose these locations may benefit from future price growth.

Property owners also find it easier to sell homes in good locations. Buyers usually spend less time deciding because the location already meets many of their needs.

Dublin Continues to Attract Home Buyers and Investors

Dublin remains one of the strongest property markets in Ireland. The city offers employment across technology, finance, healthcare, education, and many other industries. This creates steady demand for housing throughout the city.

Many professionals choose Dublin because they want shorter travel times and easy access to workplaces. Families also prefer Dublin because they can find schools, hospitals, parks, and shopping centres within a reasonable distance. Understanding local market trends, neighbourhood demand, and long-term property value plays an important role when making buying or selling decisions. Insights shared by McGuirk Beggan Property, which combines invaluable local expertise with a dedicated, client-focused approach to deliver exceptional results for buyers and sellers alike, help people make informed choices in Dublin’s competitive market.

Investors also pay close attention to Property Location. They understand that rental demand stays higher in areas with strong employment and transport options. A Property in the right part of Dublin can attract reliable tenants and maintain stable rental income over time.

Population growth also supports the property market. As more people move into the city, competition for quality homes increases. This keeps Property Location at the centre of buying decisions.

Easy Transport Makes Daily Life Better

Transport has become one of the biggest factors when choosing a Property. People want to reach work, school, or local services without spending hours on the road each day.

Dublin offers buses, trains, trams, cycling routes, and major road connections. Buyers often search for Property near these transport options because they improve daily convenience.

Living near public transport can reduce travel costs and save valuable time. Many buyers also prefer locations where they can walk to shops, restaurants, schools, and healthcare services instead of depending on a car.

A Property Location with strong transport links also attracts future buyers. This makes the home easier to sell if the owner decides to move later.

Public Transport Supports Property Demand

Public transport continues to influence buyer decisions across Dublin. Areas close to train stations, tram stops, and major bus routes often receive greater interest from buyers and tenants.

Many workers travel to offices every weekday. Easy transport helps them reach work without long delays. Families also benefit because children can travel to schools and colleges more easily.

A Property located near reliable transport often maintains stronger market demand than homes in isolated areas. This gives owners more confidence in the long-term value of their investment.

Road Networks Improve Accessibility

Road connections also play an important role in Property Location. Easy access to major roads allows people to travel across Dublin and nearby counties with less effort.

People who drive to work often prefer locations that reduce travel time. Businesses also value areas with good road access because employees and customers can reach them more easily.

These advantages continue to increase demand for Property in well-connected parts of Dublin.

Schools and Education Increase Property Demand

Education remains one of the strongest reasons why families choose a specific Property Location. Parents often search for homes close to respected schools because they want shorter travel times and better learning opportunities for their children.

Many parts of Dublin offer excellent primary schools, secondary schools, colleges, and universities. These facilities make nearby Property more attractive to families.

Students also create rental demand in areas close to colleges and universities. Investors often consider these locations because they expect consistent demand throughout the year.

A Property near good educational facilities often remains attractive even during changing market conditions. Buyers continue to value education when making long-term decisions.

Common Problems Found During Property Inspections in Carlow

Property inspections play an important role in the buying and selling process. They help buyers understand the true condition of a property before making a decision. They also help sellers identify issues that may affect a sale. In Carlow, many homes and commercial buildings face problems that develop over time due to age, weather, maintenance issues, or construction defects.

Property inspections provide a detailed review of a building’s condition. A professional inspector examines key areas of the property and identifies defects that may require repair. These inspections help people make informed decisions and reduce the risk of unexpected expenses after a purchase.

This article explains the most common problems found during property inspections in Carlow and why regular inspections remain important for every property owner.

Structural Problems in Properties

Structural issues are among the most serious findings during property inspections. These problems can affect the safety, stability, and value of a property.

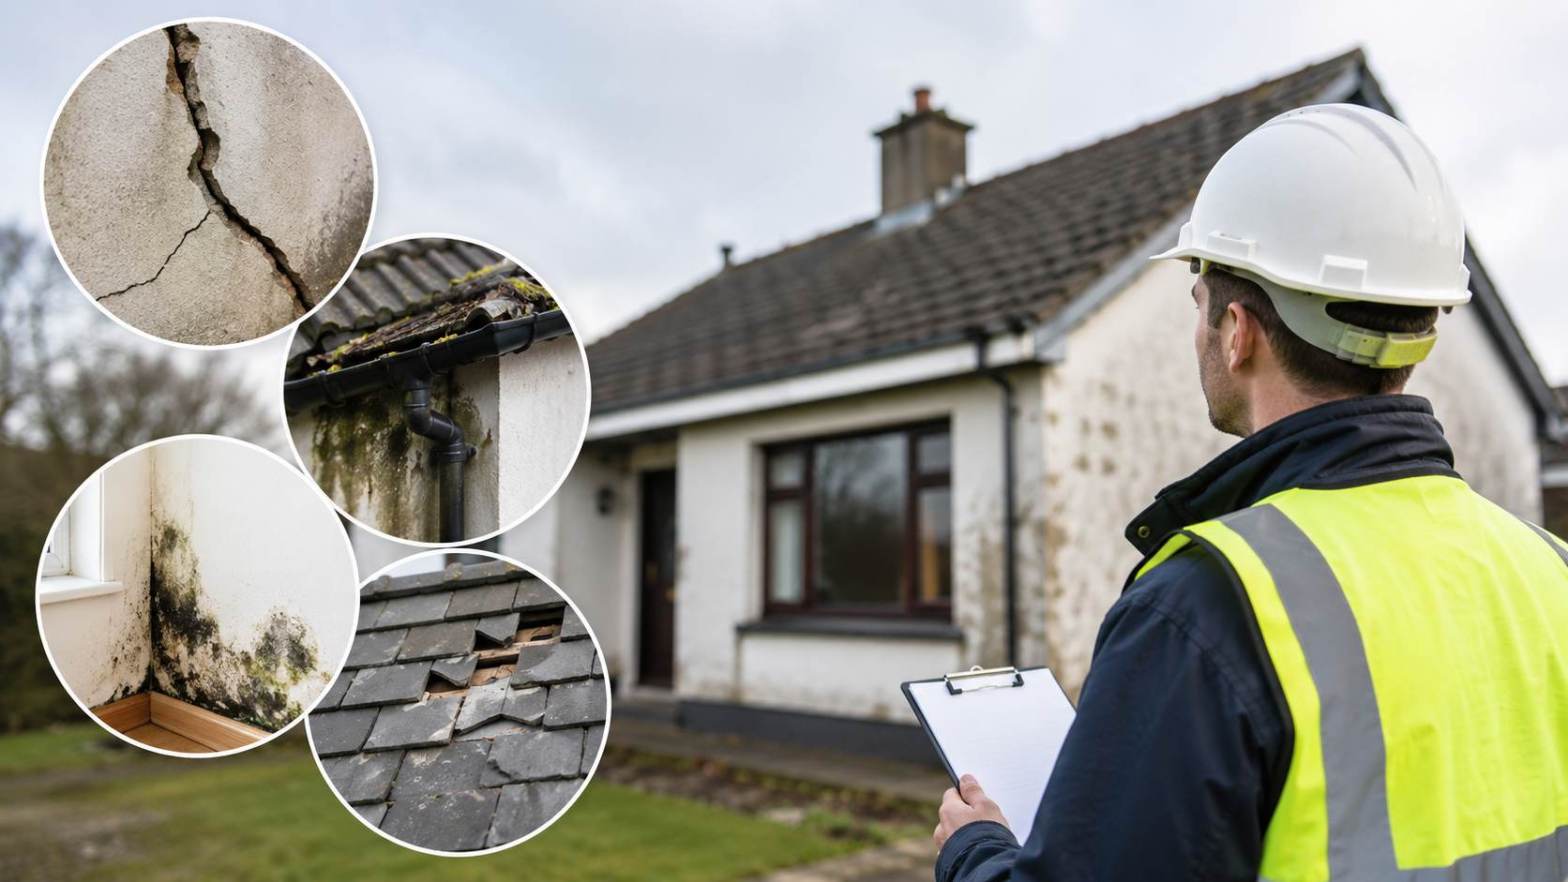
Inspectors often find cracks in walls, ceilings, and foundations. Small cracks may result from normal settlement, but large cracks can indicate movement within the structure. Foundation problems can cause floors to become uneven and doors or windows to stop functioning properly.

In some cases, inspectors discover signs of poor construction work or damage caused by moisture. Structural repairs often require professional assessment and can involve significant costs. Early detection helps property owners address problems before they become worse.

Damp and Moisture Issues

Dampness is a common concern in many properties throughout Carlow. Moisture can enter a building through damaged roofs, leaking pipes, poor ventilation, or defective external walls.

During property inspections, inspectors frequently find damp patches on walls and ceilings. These areas may show discoloration, peeling paint, or damaged plaster. Excess moisture creates conditions that support mold growth and can affect indoor air quality.

Persistent damp problems may also weaken building materials over time. Regular inspections help identify the source of moisture and allow property owners to carry out repairs before major damage occurs.

Rising Damp

Rising damp occurs when groundwater moves upward through walls. This issue usually develops when the damp-proof course fails or becomes damaged.

Inspectors often identify rising damp by looking for tide marks, damaged paint, and crumbling plaster near the lower sections of walls. If left untreated, rising damp can affect the appearance and strength of internal surfaces.

Condensation Problems

Condensation develops when warm air meets cold surfaces. Bathrooms, kitchens, and poorly ventilated rooms often experience this issue.

Property inspections commonly reveal condensation around windows, walls, and ceilings. Excess condensation can encourage mold growth and create unpleasant living conditions.

Roofing Defects

The roof protects the entire property from weather conditions. Damage to the roof can lead to water penetration and structural deterioration.

Inspectors often discover broken tiles, loose slates, damaged flashing, and blocked gutters during property inspections. Older properties in Carlow may show signs of roof wear due to long-term exposure to rain and wind.

Water entering through roof defects can damage ceilings, insulation, timber structures, and electrical systems. Regular roof maintenance helps reduce repair costs and extends the life of the property.

Damaged Roof Coverings

Roof coverings naturally deteriorate over time. Missing or cracked tiles allow water to enter the building.

Inspectors carefully examine roof surfaces to identify defects that may require repair or replacement. Early action can prevent further damage to the property.

Blocked Gutters and Downpipes

Blocked drainage systems prevent rainwater from flowing away properly. Overflowing water can damage walls, foundations, and landscaping.

Property inspections often reveal gutters filled with leaves, dirt, and debris. Cleaning these systems regularly helps protect the property from water-related damage.

Electrical System Problems

Electrical defects are frequently found during property inspections. Some issues result from aging systems, while others arise from poor installation work.

Inspectors may identify outdated wiring, overloaded circuits, damaged sockets, or missing safety devices. Older properties often require electrical upgrades to meet current safety standards.

Electrical problems increase the risk of fire and personal injury. A qualified electrician should assess and repair any defects identified during the inspection process.

Plumbing and Drainage Issues

Plumbing systems experience wear and tear over time. Leaks and drainage problems can cause significant damage if they remain unnoticed.

Property inspections often reveal leaking pipes, faulty fixtures, low water pressure, and drainage blockages. Water leaks may damage floors, walls, and ceilings while increasing utility costs.

Inspectors also check for signs of corrosion and deterioration within the plumbing system. Addressing these issues early helps maintain the condition of the property and prevents larger repairs.

Hidden Water Leaks

Some leaks remain hidden behind walls, under floors, or within ceilings. These leaks can continue for long periods before becoming visible.

Inspectors use visual evidence and moisture indicators to identify areas that may require further investigation. Early detection helps reduce water damage and repair expenses.

Drainage Defects

Drainage problems can affect both residential and commercial property. Blocked or damaged drains may cause unpleasant odors and water backup.

Property inspections help identify drainage issues before they create health or structural concerns.

Insulation and Energy Efficiency Concerns

Many property inspections in Carlow reveal problems related to insulation and energy efficiency. Poor insulation increases heating costs and reduces indoor comfort.

Inspectors evaluate roof insulation, wall insulation, and window performance. Older properties often lack modern insulation standards and may lose heat through various parts of the building. When reviewing a property’s condition, buyers often rely on local market knowledge and trusted agencies such as REA Sothern, established in Carlow for over 50 years and specialising in Residential & Commercial sales, valuations, and exclusive off-market opportunities, to better understand factors that can influence long-term property value.

Improving insulation can lower energy consumption and improve overall property performance. Buyers often consider energy efficiency when assessing a property’s long-term value.

Timber Damage and Wood Rot

Timber components form part of many residential and commercial properties. Moisture exposure can cause timber decay and reduce structural strength.

Property inspections frequently uncover wood rot in roof timbers, floor joists, window frames, and door frames. Rot develops when timber remains damp for extended periods.

Inspectors examine timber elements for signs of softness, discoloration, and deterioration. Repairing moisture sources helps prevent future timber damage.

Wet Rot

Wet rot develops when timber remains exposed to moisture. It weakens wooden structures and can spread to nearby areas.

Inspectors often find wet rot in roof spaces, basements, and areas affected by leaks.

Dry Rot

Dry rot can spread through timber and masonry more aggressively than wet rot. This condition requires prompt treatment to prevent extensive damage.

Property inspections help identify dry rot before it affects larger sections of the property.

Window and Door Defects

Windows and doors contribute to security, insulation, and weather protection. Property inspections often reveal defects that affect performance and comfort.

Inspectors may find damaged frames, broken seals, faulty locks, and poor fitting components. These issues can lead to drafts, moisture entry, and heat loss.

Repairing defective windows and doors helps improve energy efficiency and protects the property from weather-related damage.

Pest Infestations

Pest activity is another issue sometimes discovered during property inspections. Rodents, insects, and other pests can damage building materials and create health concerns.

Inspectors look for signs such as droppings, nesting materials, damaged wood, and entry points. Early identification allows property owners to arrange treatment before infestations grow larger.

Regular maintenance and proper sealing of access points help reduce the risk of pest problems.

Why Property Inspections Matter in Carlow

Property inspections provide valuable information about the condition of a building. They help buyers avoid unexpected repair costs and allow sellers to address issues before listing a property.

In Carlow, factors such as weather exposure, aging buildings, and maintenance challenges can contribute to property defects. A professional inspection helps identify these concerns and supports informed decision-making.

Property inspections also help property owners plan maintenance work and protect the long-term value of their investment. Whether someone is buying, selling, or maintaining a property, inspections remain an important step in responsible property ownership.

Conclusion

Property inspections help uncover issues that may affect safety, value, and future maintenance costs. Common findings in Carlow include structural defects, damp problems, roofing damage, electrical faults, plumbing issues, insulation concerns, timber decay, window defects, and pest activity.

A thorough inspection provides a clear picture of a property’s condition. Early identification of problems allows property owners to take action before damage becomes more severe. For anyone involved in real estate transactions, professional property inspections remain one of the most effective ways to protect a property investment in Carlow.

Why East Tennessee Homes Need Storm-Resistant Roofing

East Tennessee faces many weather problems each year. Strong rain, high winds, hail, and heavy storms often damage homes across the region. These weather conditions place pressure on roofing systems. Many homeowners deal with roof leaks, missing shingles, and water damage after storms.

Storm-Resistant Roofing gives better protection during severe weather. It helps reduce damage and lowers repair costs over time. East Tennessee Homes need strong Roofing systems because the local climate changes quickly during different seasons. Storm-resistant materials improve safety and increase roof life.

Homeowners who invest in stronger Roofing materials protect their property and avoid costly repairs. A durable roof also improves home value and supports long-term performance.

Weather Conditions in East Tennessee

East Tennessee experiences different types of weather throughout the year. Spring and summer storms bring heavy rain and strong wind, while winter often causes snow and ice buildup on roofs. These conditions weaken standard roofing materials over time and increase the risk of leaks, missing shingles, and structural damage. Homeowners who invest in reliable roofing services Greeneville can better protect their properties from seasonal storm damage and long-term moisture issues. Many Tennessee homes are located near hills, wooded areas, and open land, which increases exposure to falling branches, wind gusts, and other weather-related roofing problems during severe storms.

Storm-Resistant Roofing helps homes handle these conditions more effectively. Stronger materials stay secure during wind and protect the home from moisture damage.

Common Roofing Problems After Storms

Wind Damage

High winds often remove shingles from the roof. Missing shingles expose the inner layers of the Roofing system. Water then enters the structure and damages ceilings, walls, and insulation.

Storm-Resistant Roofing uses stronger fastening systems and durable shingles. These materials reduce the chance of wind-related damage.

Water Leaks

Heavy rain places pressure on weak Roofing systems. Small gaps around vents, flashing, or damaged shingles allow water to enter the home. Moisture inside the attic can lead to mold growth and wood damage.

A storm-resistant roof improves water protection. It creates stronger sealing around vulnerable areas.

Hail Damage

Hail impacts can crack or break roofing materials. Damaged shingles lose their protective surface. Sunlight and rain then weaken the roof more quickly.

Storm-Resistant Roofing materials often include impact-resistant shingles. These products handle hail better than standard shingles.

Tree Damage

East Tennessee has many wooded areas. Storms can break tree branches and drop debris onto roofs. Weak Roofing materials crack under heavy impact.

Storm-resistant systems provide better strength against falling debris.

Benefits of Storm-Resistant Roofing

Better Protection During Severe Weather

Storm-Resistant Roofing gives homes stronger defense during storms. Durable materials resist wind uplift, water entry, and impact damage. This protection keeps the structure safer during bad weather.

East Tennessee Homes benefit from stronger Roofing because storms occur often in the area.

Longer Roof Life

Standard Roofing materials wear down faster after repeated storms. Constant repairs shorten roof life and increase costs.

Storm-resistant materials last longer because they handle harsh weather more effectively. Homeowners spend less money on maintenance and replacements.

Lower Repair Costs

Roof repairs after storms can become expensive. Water damage, mold growth, and structural repairs increase total costs.

Storm-Resistant Roofing reduces the chance of severe damage. Fewer repairs help homeowners save money over time.

Improved Energy Efficiency

A strong Roofing system supports better insulation. It helps maintain indoor temperatures during hot summers and cold winters.

Energy-efficient Roofing reduces heating and cooling costs for Tennessee Homes.

Higher Home Value

Buyers often prefer homes with durable Roofing systems. A storm-resistant roof increases property appeal because buyers know the home has better protection.

This feature can improve resale value in areas with frequent storms.

Best Roofing Materials for East Tennessee Homes

Asphalt Impact-Resistant Shingles

Impact-resistant asphalt shingles remain one of the most popular Roofing choices. These shingles resist hail and wind damage better than standard asphalt products.

They also provide a cost-effective solution for many Tennessee Homes.

Metal Roofing

Metal Roofing offers strong weather resistance. It handles heavy rain, wind, and hail effectively. Metal roofs also last longer than many traditional Roofing materials.

Many homeowners choose metal Roofing because it requires less maintenance.

Architectural Shingles

Architectural shingles provide extra thickness and durability. They resist wind damage better than basic three-tab shingles.

These shingles also improve home appearance while offering better storm protection.

Synthetic Roofing Materials

Synthetic Roofing products imitate slate or wood but provide higher durability. These materials resist moisture, impact, and UV damage.

Homeowners who want long-lasting Roofing often consider synthetic options.

Importance of Proper Roof Installation

Strong materials alone cannot fully protect a home. Proper installation also plays a major role in Roofing performance.

Poor installation creates weak points that allow water leaks and wind damage. Loose flashing, weak fasteners, and poor sealing reduce roof strength.

Professional Roofing contractors understand local weather conditions in East Tennessee. They install materials correctly and follow safety standards.

A properly installed Storm-Resistant Roofing system performs better during severe weather events.

Roof Maintenance Helps Prevent Damage

Regular roof maintenance improves roof life and supports storm protection. Small issues can grow into larger problems if homeowners ignore them.

Homeowners should inspect Roofing systems after major storms. They should look for missing shingles, water stains, and damaged flashing.

Cleaning gutters also helps protect Tennessee Homes. Blocked gutters cause water buildup near the roof edge. Standing water increases leak risks.

Professional roof inspections help identify hidden damage before problems become severe.

Signs Your Roof Needs Replacement

Frequent Leaks

Repeated leaks often indicate major Roofing problems. Temporary repairs may no longer solve the issue.

Missing or Curled Shingles

Damaged shingles reduce roof protection. Curling and missing shingles expose the roof to water and wind.

Mold or Water Stains

Water stains on ceilings or walls often signal Roofing failure. Moisture inside the home can create mold problems.

Roof Age

Older Roofing systems become weaker over time. Many asphalt roofs last around 20 to 25 years. Storm exposure may shorten roof life further.

Homeowners should consider Storm-Resistant Roofing when replacing older roofs.

Insurance Benefits of Storm-Resistant Roofing

Some insurance companies offer discounts for storm-resistant Roofing systems. Durable materials reduce the risk of expensive storm claims.

Homeowners should ask their insurance provider about possible savings. Impact-resistant shingles and stronger Roofing materials may qualify for reduced premiums.

Insurance benefits help offset the cost of roof upgrades.

Choosing the Right Roofing Contractor

Selecting the right contractor is important for Roofing quality. Homeowners should choose experienced professionals with local knowledge.

Reliable contractors inspect the roof carefully and explain material options clearly. They also provide written estimates and warranty information.

Homeowners should review contractor licenses, insurance coverage, and customer feedback before starting a Roofing project.

A skilled Roofing contractor improves installation quality and long-term roof performance.

How Storm-Resistant Roofing Supports Home Safety

Roofing systems protect the entire structure of a home. A damaged roof increases risks during severe weather.

Storm-Resistant Roofing helps prevent water entry, mold growth, and structural weakening. It also reduces the chance of roof failure during strong winds.

Families inside Tennessee Homes gain better safety during storms when the roof remains secure and stable.

Conclusion

East Tennessee weather creates serious challenges for homeowners. Strong storms, hail, wind, and heavy rain place constant pressure on Roofing systems. Weak roofs often develop leaks, missing shingles, and structural damage after severe weather.

Storm-Resistant Roofing provides stronger protection for Tennessee Homes. Durable materials reduce storm damage, lower repair costs, and improve roof life. Proper installation and regular maintenance also help roofs perform better over time.

Homeowners who invest in high-quality Roofing systems protect their homes and improve long-term property value. A storm-resistant roof gives better security, better durability, and greater peace of mind during East Tennessee storms.

How Soccer Training Impacts a Child’s Confidence

Socer training plays a key role in a child’s growth. It builds skills, habits, and strong thinking patterns. A child learns how to act, decide, and respond in different situations. A socer club gives a safe place where a child can learn and improve. This process supports Child’s Confidence in a steady and natural way.

Confidence grows when a child takes action and sees progress. Socer training gives many chances for action. A child runs, passes, shoots, and works with a team. Each activity builds trust in their own ability. This trust becomes confidence.

Understanding Child’s Confidence

Child’s Confidence means a child believes in their own ability. The child feels ready to try new tasks. The child accepts both success and failure. Confidence does not mean a child always wins. Confidence means a child keeps trying.

A child with strong confidence speaks clearly. The child joins group activities without fear. The child handles mistakes with a calm mind. Socer training supports these habits through regular practice and teamwork.

How Socer Training Builds Basic Skills

Soccer training teaches basic physical skills. A child learns balance, speed, and control through structured sessions. These skills improve body awareness and help the child move with confidence. When a child controls their body well, the child feels more secure during play and practice.

A coach gives clear instructions and guides each step with purpose. In focused sessions like soccer private training, the child receives direct feedback and can correct mistakes quickly. This process builds a clear link between effort and outcome. The child understands that practice leads to improvement, which supports the child’s confidence over time.

A soccer club also uses drills to repeat key actions such as passing and shooting. Repetition strengthens muscle memory and sharpens skills. As skill improves, the child develops trust in their ability. This trust helps build strong and lasting confidence on and off the field.

The Role of a Socer Club Environment

A socer club creates a structured environment. The child follows rules and schedules. This structure builds discipline. Discipline helps the child stay focused and calm.

The socer club also creates a social space. The child meets teammates and coaches. The child learns how to communicate and cooperate. These social skills support confidence in daily life.

A coach plays an important role. The coach gives feedback and support. Positive feedback helps the child feel valued. Clear feedback helps the child improve. Both actions support Child’s Confidence.

Teamwork and Social Growth

Socer training requires teamwork. A child passes the ball and supports teammates. The child learns that success depends on group effort. This idea builds respect and trust.

A child learns how to share responsibility. The child understands that each player has a role. This understanding builds a sense of belonging. A strong sense of belonging supports confidence.

The child also learns how to handle conflict. Small issues may happen during games. The child learns to solve problems through communication. This skill helps the child stay calm and confident.

Handling Success and Failure

Socer training teaches both winning and losing. A child wins some games and loses others. This experience builds emotional strength.

When a child wins, the child feels proud. The coach guides the child to stay humble. When a child loses, the child may feel upset. The coach helps the child learn from mistakes.

This balanced experience teaches the child to stay stable. The child does not fear failure. The child sees failure as part of learning. This mindset supports strong Child’s Confidence.

Goal Setting and Achievement

Socer training uses clear goals. A child may aim to improve passing or scoring. The coach sets small and simple targets.

The child works step by step to reach these goals. When the child reaches a goal, the child feels success. This success builds confidence.

Goal setting also teaches planning. The child learns to focus on one task at a time. This habit improves decision-making. Better decisions support confidence in many areas.

Physical Fitness and Mental Strength

Socer training improves physical fitness. A child becomes stronger and more active. A healthy body supports a healthy mind.

Exercise reduces stress and improves mood. A child feels more relaxed after training. A calm mind helps the child think clearly.

Mental strength grows through effort. A child faces challenges during training. The child keeps trying and does not give up. This habit builds strong Child’s Confidence.

Decision-Making Skills

Socer training requires quick decisions. A child decides when to pass, shoot, or move. These decisions happen in real time.

The child learns to observe and act. The child learns to trust their own judgment. This trust builds confidence.

Decision-making also improves focus. The child stays alert during the game. This focus helps the child in school and daily tasks.

Communication Skills

A socer club encourages communication. Players talk during games and practice. A child calls for the ball and gives signals.

This communication builds clarity. The child learns to express thoughts in a simple way. Clear expression supports confidence.

The child also learns to listen. Listening helps the child understand instructions. Good understanding improves performance and builds trust.

Leadership Development

Socer training offers chances for leadership. A child may lead a small group or guide teammates. These roles build responsibility.

Leadership teaches decision-making and support. The child learns to guide others with respect. This experience builds strong Child’s Confidence.

A child who leads also learns accountability. The child accepts both success and mistakes. This balance builds maturity.

Building Routine and Discipline

Socer training follows a routine. The child attends practice at set times. The child follows rules and instructions.

Routine builds discipline. Discipline helps the child manage time. The child learns to complete tasks on time.

A disciplined child feels more in control. This control supports confidence in daily life.

Support from Coaches and Parents

Coaches and parents support the child’s journey. A coach gives guidance during training. A parent gives support at home.

Positive support builds trust. The child feels safe to try new things. This safety supports Child’s Confidence.

Clear communication between coach and parent helps the child grow. Both sides guide the child in a simple and clear way.

Long-Term Impact on Child’s Confidence

Socer training creates long-term benefits. A child carries skills into school and life. The child becomes more active, social, and focused.

Confidence built through socer training stays strong over time. The child faces challenges with a stable mindset. The child believes in their own ability.

A socer club helps the child grow step by step. Each session adds value. Each game adds experience. This steady process builds strong Child’s Confidence.

Conclusion

Socer training supports many areas of growth. It builds physical skills, social skills, and mental strength. A socer club creates a safe and structured space for learning.

Child’s Confidence grows through action, support, and experience. A child learns to trust their ability. The child learns to handle success and failure.

Socer training gives real-life lessons. These lessons help the child grow into a confident and capable person.

How to Understand Your Finances During Divorce in Ireland

Divorce affects many parts of life. Finances often create the most stress during the process. A person must review income, assets, debts, and future needs. A clear view of money matters helps both partners make fair decisions.

Divorce in Ireland follows legal rules that focus on fairness. Courts aim to divide financial resources in a way that supports both spouses and any children. Each partner must provide clear financial information. This step helps the court or mediators understand the financial situation.

Finances in Ireland may include property, savings, pensions, income, and debts. A careful review of these areas helps both spouses understand their rights and duties. This article explains how finances work during divorce in Ireland and what steps help people manage this process.

The Legal Framework of Divorce in Ireland

Divorce in Ireland follows rules set by Irish law. The court reviews the financial position of both spouses before making decisions. The court aims to ensure proper support for both partners and for any children.

Irish law requires proof that the marriage has broken down. The law also requires the spouses to live apart for a set period before divorce. Once a court accepts the divorce request, it examines the financial position of both partners.

The court reviews income, property, savings, pensions, and debts. The court then decides how these resources should be divided. The goal is fairness and financial stability for both sides.

Finances in Ireland must appear in a clear financial statement. Each spouse must provide accurate details. This information helps the court understand the full financial situation.

Why Financial Planning Matters During Divorce

Financial planning helps people avoid stress during divorce in Ireland. Divorce often changes a person’s income, expenses, and living situation. A clear plan helps people prepare for these changes. Reliable information also helps individuals understand the possible financial impact of separation. Many people review transparent cost breakdowns and guidance from platforms like Equitable Divorce to better understand the financial process of divorce in Ireland and plan their next steps with clarity.

A person should review all financial records early in the process. These records include bank accounts, tax returns, property documents, and loan statements. Accurate records help both spouses understand the financial picture.

Financial planning also helps people set future goals. A person may need to adjust spending, housing, or savings plans. Careful planning reduces uncertainty and supports financial stability.

Finances in Ireland also include long-term security. Pension rights and future income play an important role. A person should review these areas with care before final agreements.

Identifying Marital Assets

Marital assets form a major part of financial discussions during divorce in Ireland. Assets include any property or financial resource owned by one or both spouses.

Common marital assets include:

  • Family homes
  • Investment properties
  • Savings accounts
  • Business ownership
  • Vehicles
  • Pension funds

Each spouse must disclose these assets in a financial statement. Accurate disclosure ensures transparency during the divorce process.

The court reviews the value of these assets. The court then decides how the assets should be shared. The court considers each spouse’s financial needs, contributions, and responsibilities.

Finances in Ireland often involve property. Property may hold high value. For this reason, property valuation often becomes an important step during divorce.

Understanding Debt Responsibilities

Debt forms another key part of finances during divorce in Ireland. Couples often share debts that they created during the marriage. These debts may include mortgages, loans, or credit card balances.

The court reviews all debts linked to the marriage. The court then decides how each spouse should manage these debts after divorce.

Debt responsibility depends on several factors. These factors include income levels, financial capacity, and the purpose of the debt. For example, a loan taken for family expenses may involve both spouses.

Clear records help explain how debts developed. Financial statements, loan documents, and bank records help provide accurate information.

A clear understanding of debt prevents future disputes. It also helps each spouse prepare for financial independence after divorce.

Property and the Family Home

The family home often creates emotional and financial questions during divorce in Ireland. The home may represent the largest asset in the marriage.

The court reviews several factors before deciding about the home. These factors include:

  • Housing needs of both spouses
  • Care arrangements for children
  • Financial ability to maintain the property

In some cases, one spouse remains in the home. In other cases, the property may be sold and the money divided. The court selects the option that supports fairness and stability.

Finances in Ireland often require a professional valuation of the property. This valuation helps both parties understand the real market value of the home.

Property decisions often shape the financial future of both spouses. For this reason, property discussions require careful thought and clear financial analysis.

Pension Rights in Divorce

Pensions hold long-term financial value during divorce in Ireland. Many people overlook pensions during financial discussions. However, pensions often represent one of the largest financial resources in a marriage.

Irish law allows pension adjustment orders. These orders allow a court to divide pension benefits between spouses.

A pension adjustment order assigns a portion of pension benefits to the other spouse. This order ensures fairness in long-term financial security.

Finances in Ireland must include pension valuation during divorce. Pension providers often provide official statements that show the current value of the pension.

Understanding pension rights helps both spouses plan for retirement. Proper evaluation ensures fair distribution of future financial benefits.

Spousal Maintenance and Financial Support

Spousal maintenance provides financial support from one spouse to the other after divorce. The court may order this support when one spouse needs financial assistance.

Maintenance depends on several factors. These factors include income levels, financial needs, and earning capacity. The court also considers childcare responsibilities and health conditions.

Maintenance may last for a fixed period or until financial stability improves. Some cases involve long-term maintenance if one spouse cannot achieve financial independence.

Finances in Ireland require accurate income records during maintenance discussions. Pay slips, tax returns, and employment records help determine financial capacity.

Clear financial information helps the court create fair maintenance arrangements.

Child Maintenance and Financial Responsibility

Children remain a priority in divorce in Ireland. Parents must support the financial needs of their children.

Child maintenance covers expenses such as:

  • Housing
  • Food
  • Education
  • Healthcare
  • Clothing

The court reviews the income and financial capacity of both parents. The court then determines a fair maintenance arrangement.

Finances in Ireland focus on the welfare of children during divorce. Courts aim to ensure stable living conditions for children after separation.

Parents may reach agreements through mediation or court orders. Clear agreements help prevent disputes and support the child’s well-being.

Financial Disclosure and Transparency

Financial disclosure forms a key step in divorce in Ireland. Each spouse must provide full details about finances.

Disclosure usually includes:

  • Income records
  • Bank accounts
  • Property ownership
  • Investments
  • Pensions
  • Debts

This process ensures transparency between both partners. Accurate disclosure prevents hidden assets or misleading financial information.

Finances in Ireland rely on honesty during this stage. Courts may reject incomplete or inaccurate financial statements.

Clear financial disclosure allows fair financial decisions. It also helps both spouses understand their financial position after divorce.

Financial Agreements and Mediation

Many couples choose mediation during divorce in Ireland. Mediation helps spouses discuss financial issues with the help of a neutral professional.

Mediation often reduces conflict. It also allows couples to reach financial agreements without a lengthy court process.

Financial agreements may include property division, debt responsibility, and maintenance arrangements. Once both parties agree, the court reviews the agreement before final approval.

Finances in Ireland often benefit from mediation because the process encourages cooperation. Couples can discuss financial matters openly and find balanced solutions.

Mediation also saves time and legal costs in many divorce cases.

Preparing for Financial Life After Divorce

Divorce creates major financial changes. A person must adjust spending, savings, and financial planning after divorce.

A good starting point involves creating a new budget. A person should review income and regular expenses. This step helps maintain financial stability.

A person may also need to review housing costs, insurance, and savings plans. Financial planning supports independence and security.

Finances in Ireland may also require new financial goals. These goals may include rebuilding savings or planning for retirement.

Professional financial advice can help people understand their options. A financial advisor can explain investment choices and budgeting strategies.

Clear financial planning allows people to move forward with confidence after divorce.

Conclusion

Divorce in Ireland involves careful financial review. The process examines assets, debts, property, pensions, and income. Courts aim to create fair outcomes for both spouses and for any children.

Finances in Ireland require clear records and honest disclosure. Accurate information helps the court or mediators understand the financial situation.

Financial planning plays an important role during this time. A person who reviews assets, debts, and future needs can make informed decisions.

Divorce creates challenges, but clear financial understanding helps reduce uncertainty. Careful financial preparation allows people to build a stable future after divorce in Ireland.

Create your own website, free on WordPress.com.Create your own website.
Start free